

Sam Bankman-Fried: This crypto entrepreneur saw his £21bn empire crumble in just three days - what happened at FTX?
Sam Bankman-Fried looked unstoppable.
The 30-year-old had built a £21bn business empire and was the CEO of FTX, the world's second-largest cryptocurrency exchange.
More than one million customers worldwide were using his platform to buy assets like Bitcoin - enticed by star-studded adverts that made everything look simple and safe.
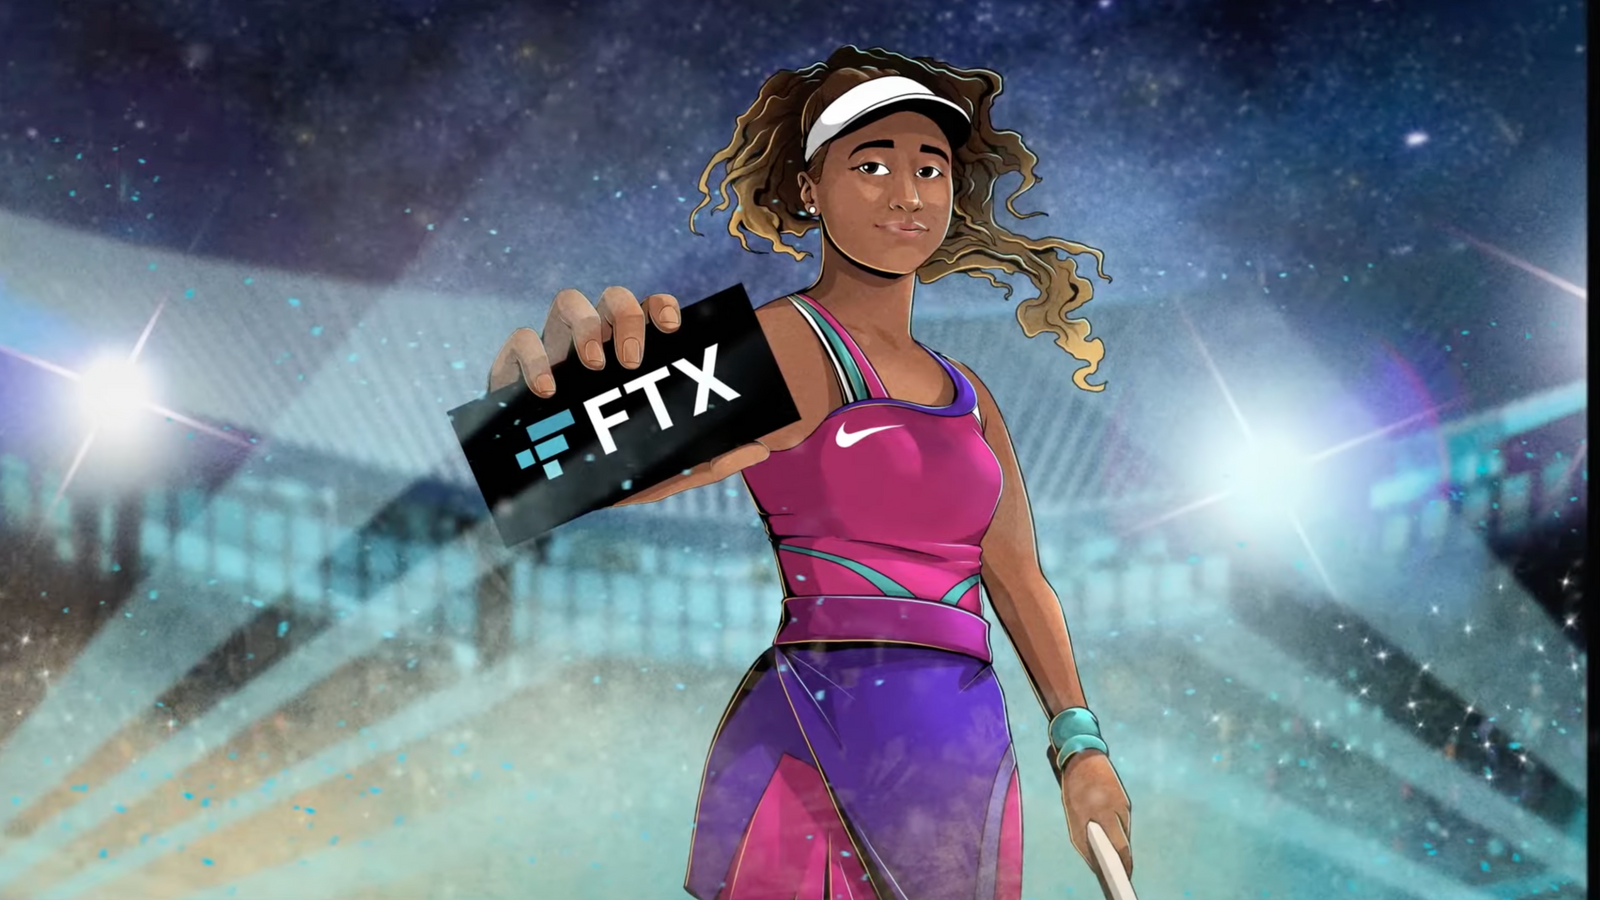 Naomi Osaka appeared in an ad for FTX
But in the space of just three days, a series of bombshell allegations led to the spectacular collapse of FTX and a bankruptcy of its own.
Bankman-Fried's personal wealth dropped by a staggering 94% in 24 hours - the biggest one-day fall ever suffered by a billionaire, according to Bloomberg.
Hundreds of thousands are locked out of their life savings - an estimated 80,000 of them in the UK.
Vast sums of money have gone missing from the exchange, amid allegations that customer funds were mismanaged.
No longer a billionaire, Bankman-Fried says his net worth has dwindled to $100,000 (£80,000) following FTX's demise - and he admitted it has been a "bad month".
But it could soon get a lot worse for Bankman-Fried. Criminal investigations have now been launched into the company's collapse, with aggrieved investors filing a flurry of lawsuits.
So what next for the deposed "Crypto King", why did his digital empire rise and fall so quickly, and where does it leave this already embattled industry?
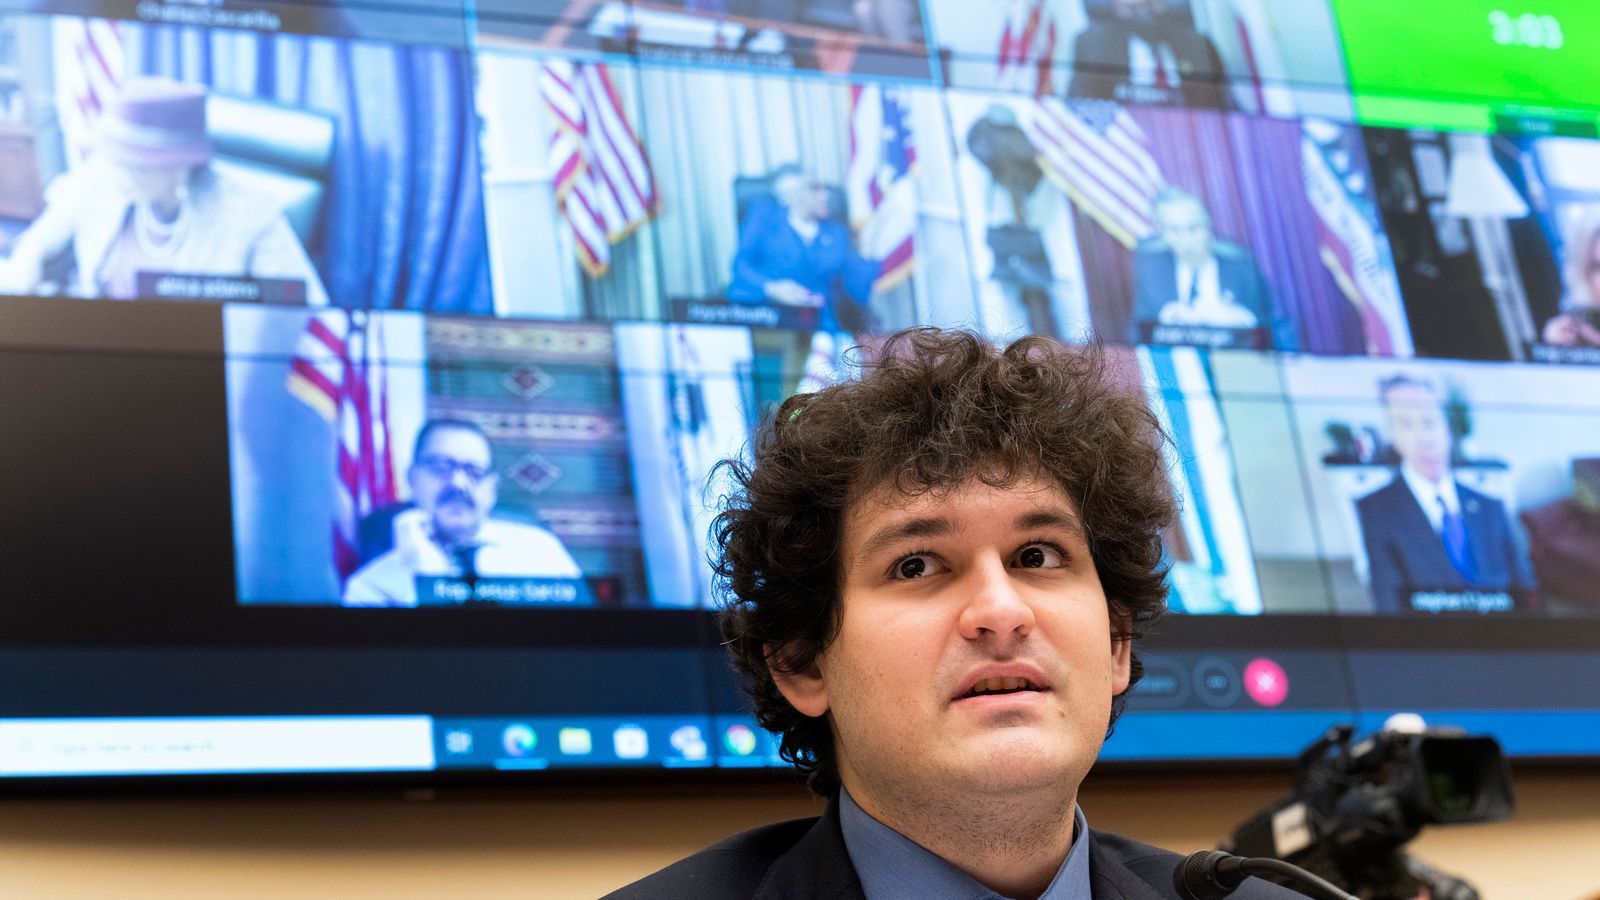
An 'altruistic' entrepreneur
Californian-born, a poster boy for "effective altruism" (getting rich in order to give money to good causes), a teetotaller and a vegan, Bankman-Fried is in many ways a far cry from the Machiavellian emperors of time gone by.
Still, SBF managed to craft an empire that would even make Julius Caesar green-eyed.
Bankman-Fried's story - which is by no means a rags-to-riches one - begins in the wealthy San Francisco Bay area, where he attended a $56,000-a-year school.
After graduating from the Massachusetts Institute of Technology, SBF moved on to Wall Street - and later set up his own trading business called Alameda Research.
His co-founder Tara Mac Aulay left the business in 2018 in part because of "concerns over risk management and business ethics".
After attending a cryptocurrency event, Bankman-Fried left the US and moved to Hong Kong, where he founded FTX.
The FTX boom
FTX was set up to allow people to buy cryptocurrencies using their pounds and dollars. It was praised for its easy-to-use interface - and made money by charging small fees for each transaction.
By July 2021, FTX had more than one million users and was the third-largest cryptocurrency exchange by volume - winning investments from major firms including SoftBank and Sequoia Capital.
In September of that year, Bankman-Fried moved his business to the tax haven of The Bahamas - in part, he claimed, because of a crackdown on crypto by China.
Once settled in the Caribbean, Bankman-Fried - an avid gamer who was once accused of playing League of Legends during a business meeting - invested in a multimillion-dollar waterfront penthouse.
The luxury property, overlooking an area used for filming the scene where Daniel Craig famously emerged from the water in Casino Royale, was also used as a home office for Bankman-Fried and up to nine of his FTX devotees.
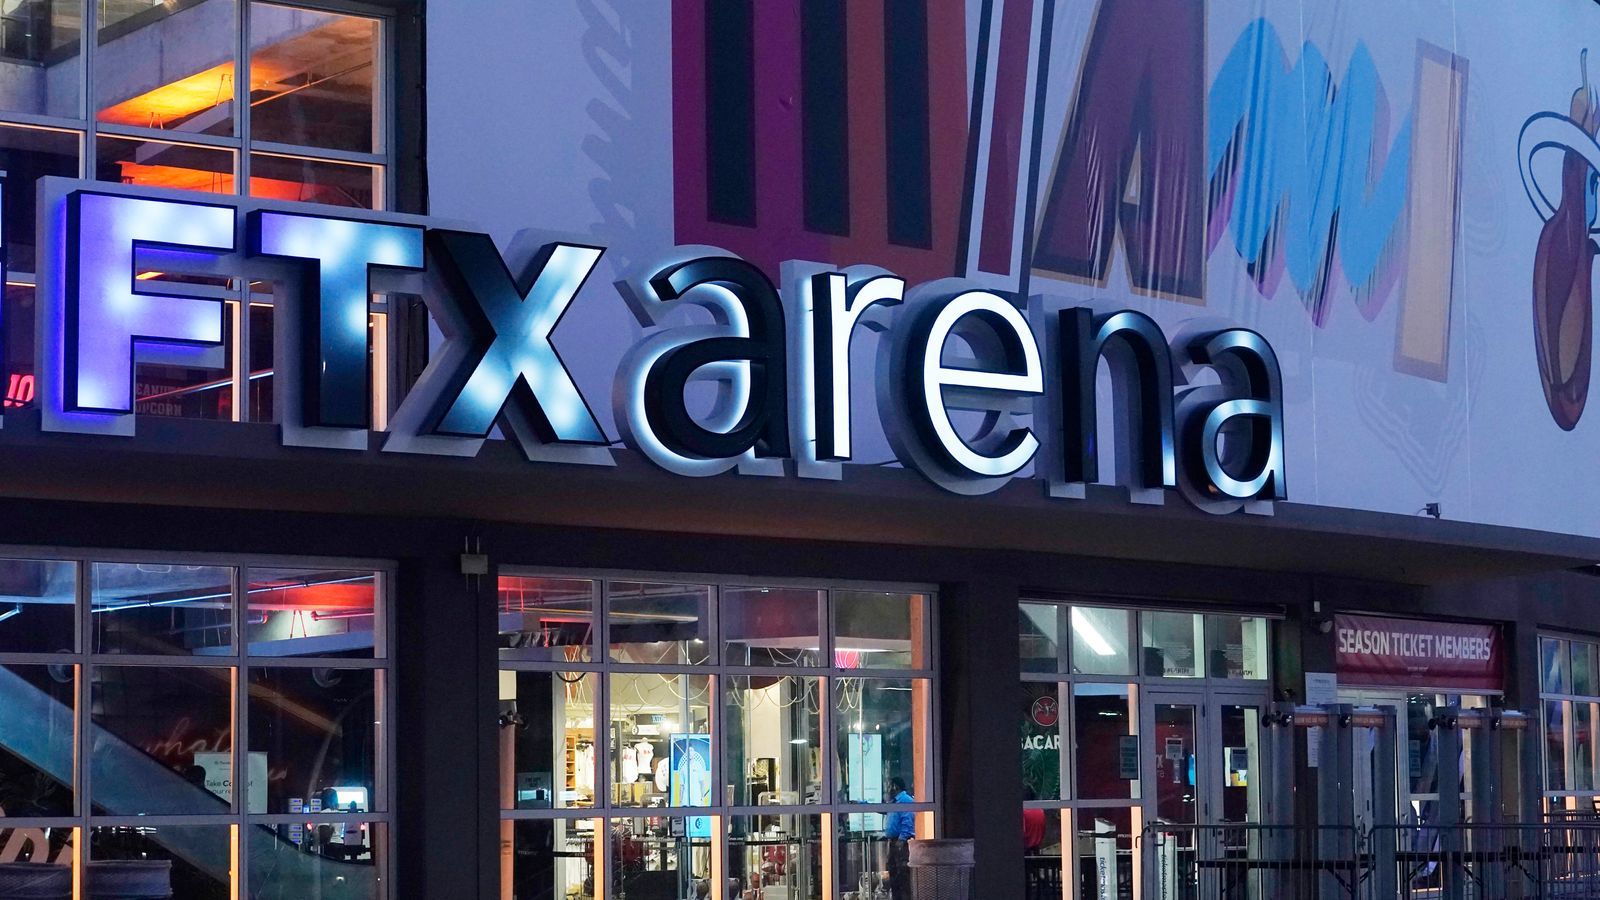
Under SBF's leadership,FTX marketed itself aggressively. It paid a reported $135m (£110m) for the naming rights to an arena used by the Miami Heat basketball team.
Tennis star Naomi Osaka and NFL legend Tom Brady entered into high-profile partnerships with the exchange - appearing in TV adverts and snapping up equity stakes in the business.
And during the Super Bowl earlier this year, FTX spent millions on a 60-second TV spot featuring Curb Your Enthusiasm star Larry David - a commercial that hasn't aged well.
The advert showed David travelling through the ages and dismissing inventions including the wheel, the fork and the toilet - zooming to the present day, where he's told about FTX being a "safe and easy way to get into crypto".
"Ehhhhh, I don't think so," the comedian says in the advert. "And I'm never wrong about this stuff. Never."
The FTX bust
In April this year, Bankman-Fried cemented his status - appearing on stage at an event with former US president Bill Clinton and ex-UK prime minister Tony Blair.
SBF also backed Joe Biden's presidential campaign against Donald Trump to the tune of more than $5m (£4.1m) - making him the politician's second-biggest financial backer.
But last month, reports began to suggest trouble was afoot at FTX because of its close ties to Bankman-Fried's first business, Alameda Research.
FTX had created its own token called FTT, which was designed to offer discounts and incentives to the exchange's customers. The total value of all the FTT tokens in circulation stood at £2.65bn - making it one of the biggest cryptocurrencies in the world.
A leaked document obtained by the crypto publication CoinDesk revealed that Alameda Research had a significant amount of FTT on its balance sheet - raising serious questions about the health of this trading firm.
That spooked Changpeng Zhao - an early investor in FTX who runs Binance, the world's biggest exchange.
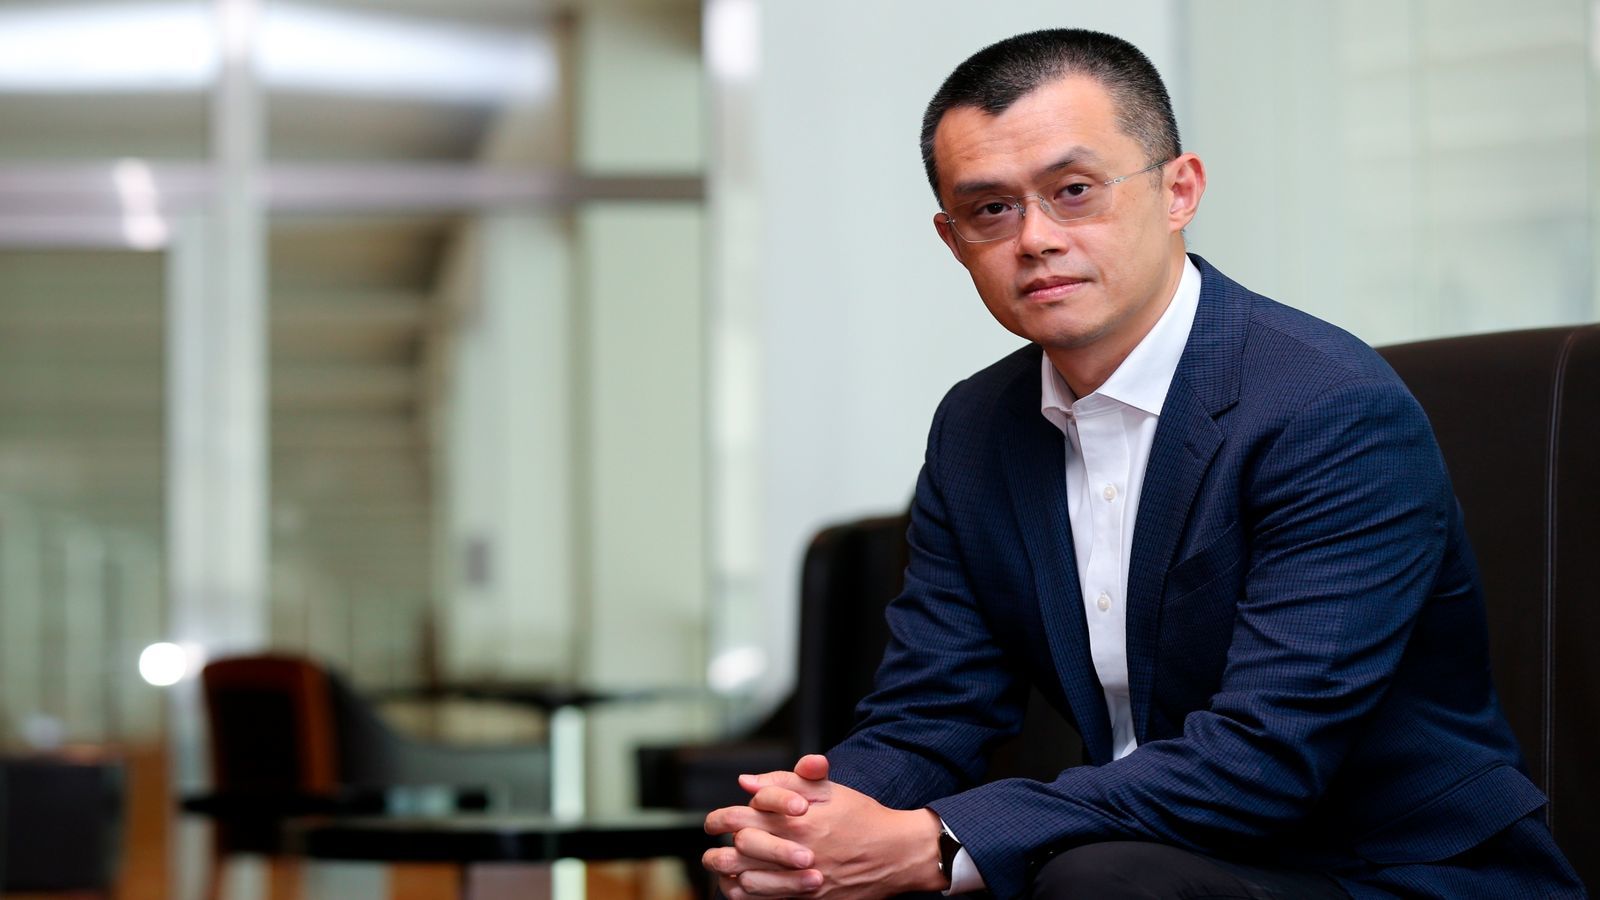 Changpeng Zhao.
In a dramatic move, Zhao, who had been feuding with Bankman-Fried over the future of crypto regulation, announced Binance would sell off the FTT tokens on its books - a haul worth $529m (£430m).
The announcement sparked a huge decline in the value of FTT, which has lost 95% of its value since the crisis began. Meanwhile, investors rushed to FTX to withdraw their crypto, fearing its collapse.
It is estimated that about $6bn (£5.2bn) worth of withdrawal requests were made in three days, pushing FTX into a financial crisis.
Binance said it would consider acquiring FTX - but one executive said it took just two hours of due diligence to conclude that the company was beyond saving.
That same day, FTX filed for bankruptcy in the US state of Delaware - with liabilities of at least $10bn (£8.2bn).
Users are now unable to withdraw their savings from the exchange, and it could be years before they see any of their money again.
Things then went from bad to worse. Hours after the bankruptcy, worried customers were dealt another blow after FTX was hacked - with officials estimating that $600m (£490m) was siphoned from the exchange.
Bankman-Fried also caused anger when he tweeted "WHAT HAPPENED", one letter at a time, in a thread over several days - leading to criticism that he was tone deaf while users were desperate for updates about what was going on.
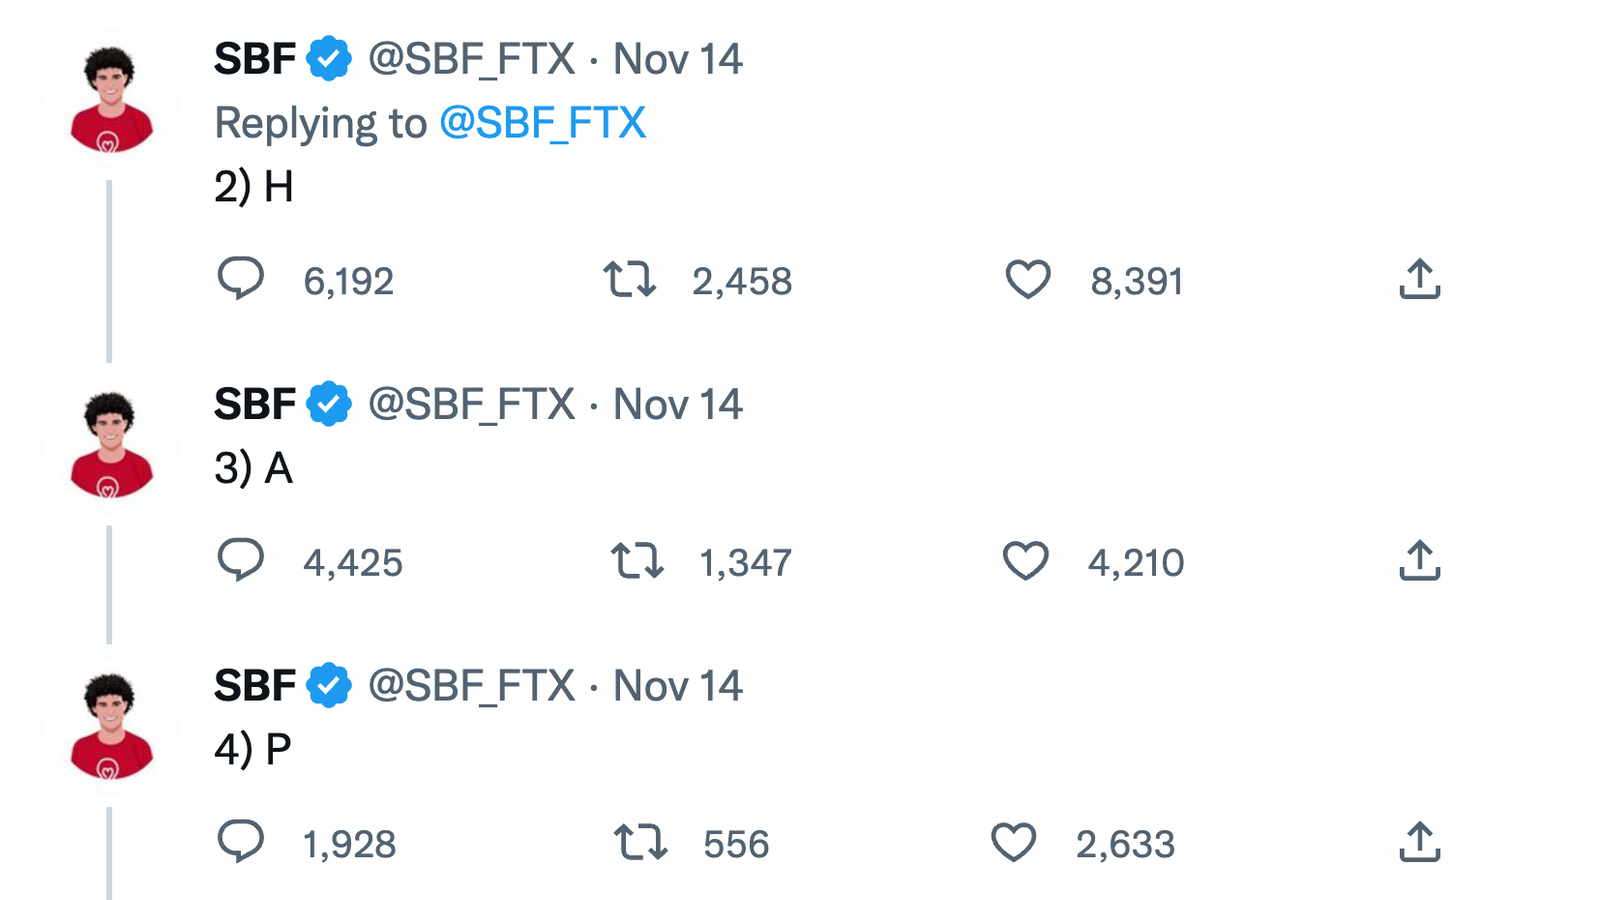
Allegations of shady business practices have since emerged - with Reuters reporting that FTX used customer funds to cover losses at its sister company Alameda Research, with up to £8bn being moved in secret. Bankman-Fried has said he "wasn't running" Alameda's operations and "didn't know exactly what was going on".
Elsewhere, it's been claimed that Bankman-Fried had established a "backdoor" in FTX's bookkeeping system that allowed money to be moved out of the business without other executives being alerted. The entrepreneur has denied that this was the case.
The Financial Times also reported that as much as $8bn (£6.5bn) in customer funds has vanished from FTX - and now, the exchange's new management has been left picking up the pieces.
FTX's new CEO is John Ray, who made his name after leading the energy firm Enron through bankruptcy proceedings in the early 2000s. That major company had collapsed amid revelations of widespread accounting fraud and corruption.
Outlining the severity of the crypto exchange's condition, Mr Ray wrote in a bankruptcy filing: "Never in my career have I seen such a complete failure of corporate controls and such a complete absence of trustworthy financial information as occurred here.
"From compromised systems integrity and faulty regulatory oversight abroad, to the concentration of control in the hands of a very small group of inexperienced, unsophisticated and potentially compromised individuals, this situation is unprecedented."
A bankruptcy lawyer for FTX's new management later said Bankman-Fried had run the company as his "personal fiefdom" - and the business has suffered "one of the most abrupt and difficult collapses in the history of corporate America".
Bankman-Fried has repeatedly apologised - saying he "f***** up" with how he handled the business - and has given a number of high-profile interviews despite being advised not to do so by lawyers.
He has also expressed fears that some customers who had crypto locked up in FTX may only receive 20% to 25% of their savings back.
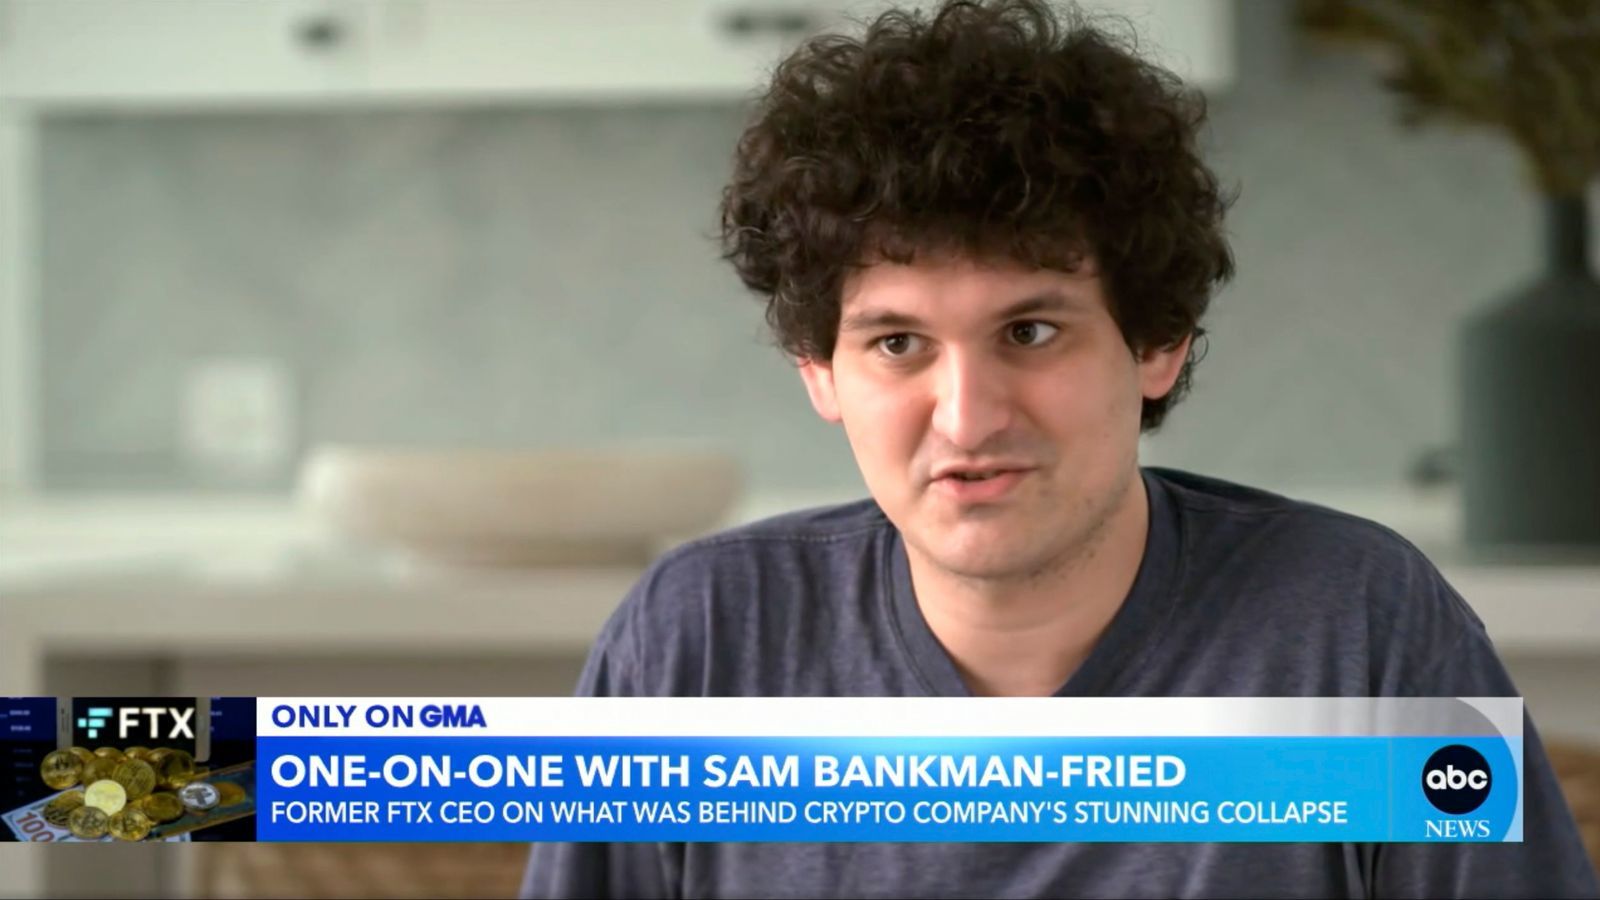
On Wednesday, he spoke at The New York Times' DealBook summit for the first time since the dramatic collapse of the business.
He said: "I didn't ever try to commit fraud on anyone. I was excited about the prospects of FTX a month ago. I saw it as a thriving, growing business. I was shocked by what happened this month."
SBF was also asked about claims that he and the co-workers in his penthouse were a polyamorous group who drifted in and out of relationships with one another and held drug-fuelled parties.
He told The New York Times: "When we had parties, we played board games and 20% of people would have three-quarters of beer each or something like that. And the rest of us would not drink anything. I didn't see any illegal drug use around me - you know, at the office or at these parties."
And speaking to Good Morning America, SBF added: "I lived with a bunch of monogamous couples when I was here, some of whom got married over the course of their time here. I don't know of any polyamorous relationships within FTX."
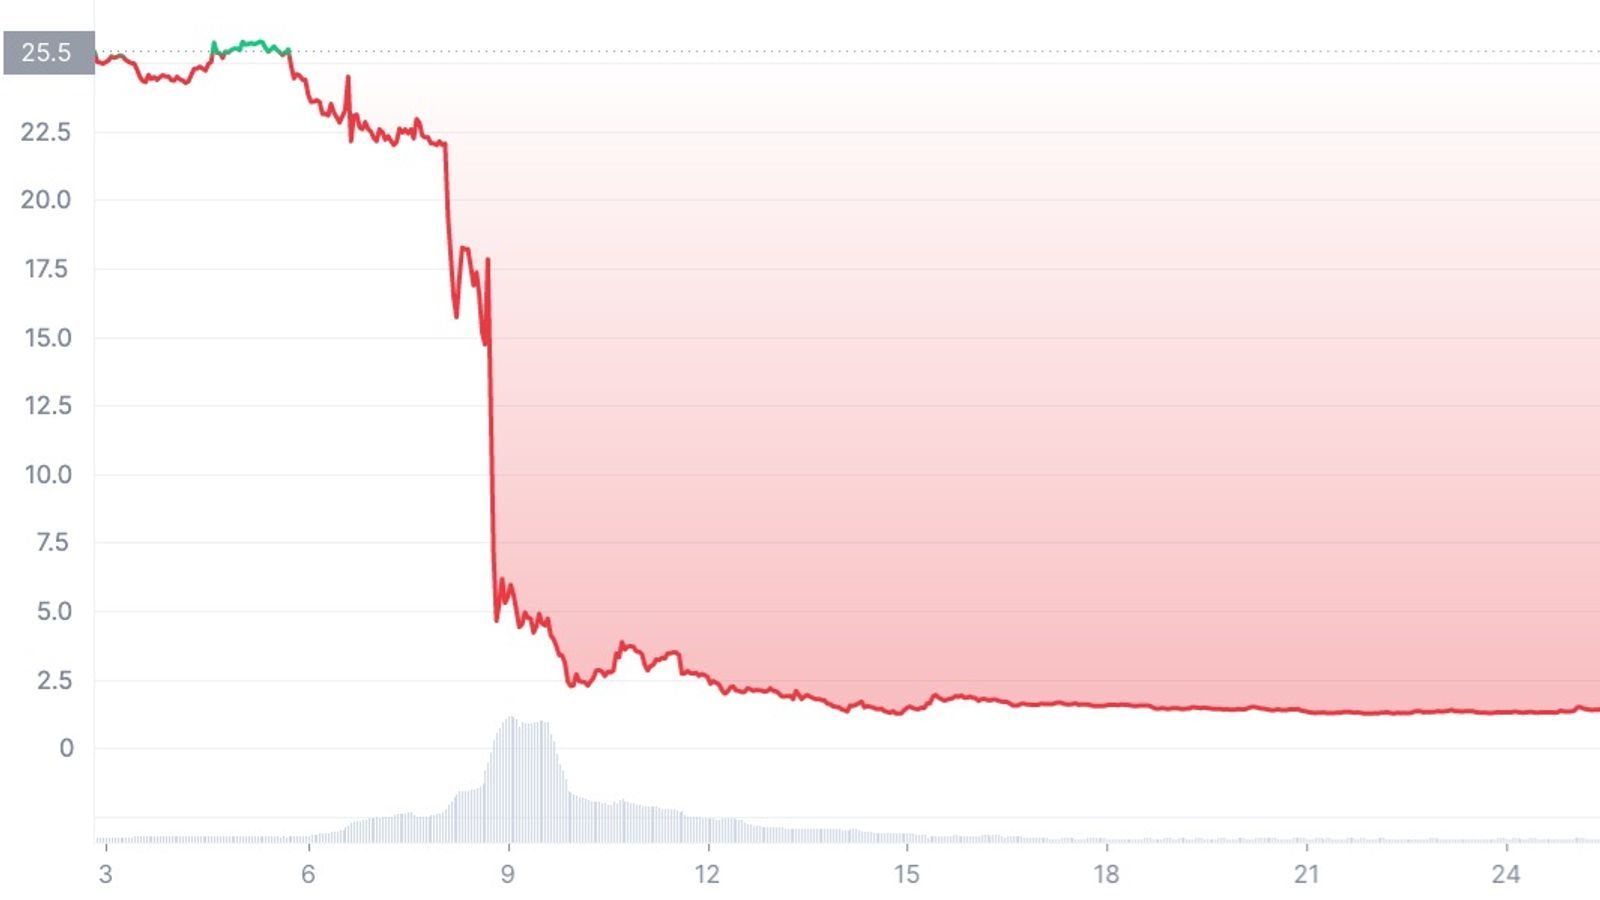 The value of FTX's FTT token has collapsed over the past month.
What about the future?
Everyday investors and some top US firms have lost out in the FTX crash.
A crypto lending company called BlockFi has now been tipped into bankruptcy as a direct result of this exchange's demise, and more may follow.
Meanwhile, the future of other businesses that FTX had acquired is uncertain.
The shockwaves have been largely contained in the crypto sector and haven't spilled over into traditional markets.
Nonetheless, experts in the field say there will be real-world ramifications going forward.
Eddie Donmez, finance influencer and global market analyst at Finimize, said crypto businesses are likely to face more regulation in the future.
He told Sky News: "In the near term, the contagion has been within the crypto market and while the near term has been very bad, terrible, for cryptocurrency what I do think is that it could be an acid test for regulation.
"While there are always bad actors involved in any industry where money is involved, this could be a good thing in the long term for crypto."
Mr Donmez also said he believed that the whole FTX episode is something that should make people sit up and listen.
He added: "This story is of interest to the public because there are some major players who have been fooled by a kid playing computer games in investment meetings.
"It shows everyone can get it wrong from time to time."
Katharine Wooller, from crypto insurance firm Coincover, added: "I think this will bring regulation. Crypto purists will say no because it is against what they believe is at the heart of crypto, but there needs to be more regulation, not less."
The collapse of FTX is another hammer blow to the credibility of cryptocurrencies - with Bitcoin's price falling by 75% since November 2021.
But Bitcoin enthusiasts say this company's demise shows why it is important for investors to store crypto on their own devices, rather than entrust it to an exchange.
There's little sign that conditions will improve in this infamously volatile sector any time soon - and if the world's second-largest exchange can go bankrupt, no crypto company is safe.