CoreWeave has lost a quarter of its stock market value in a month, exposing investor unease about the debt-funded companies supplying computing power to the artificial intelligence industry, even as demand outstrips supply.
Shares in fellow ‘neocloud’ operators Nebius, IREN and Applied Digital have fallen by roughly as much or more. Debt investors are also demanding higher returns from several firms, threatening to make their continued borrowing more expensive.
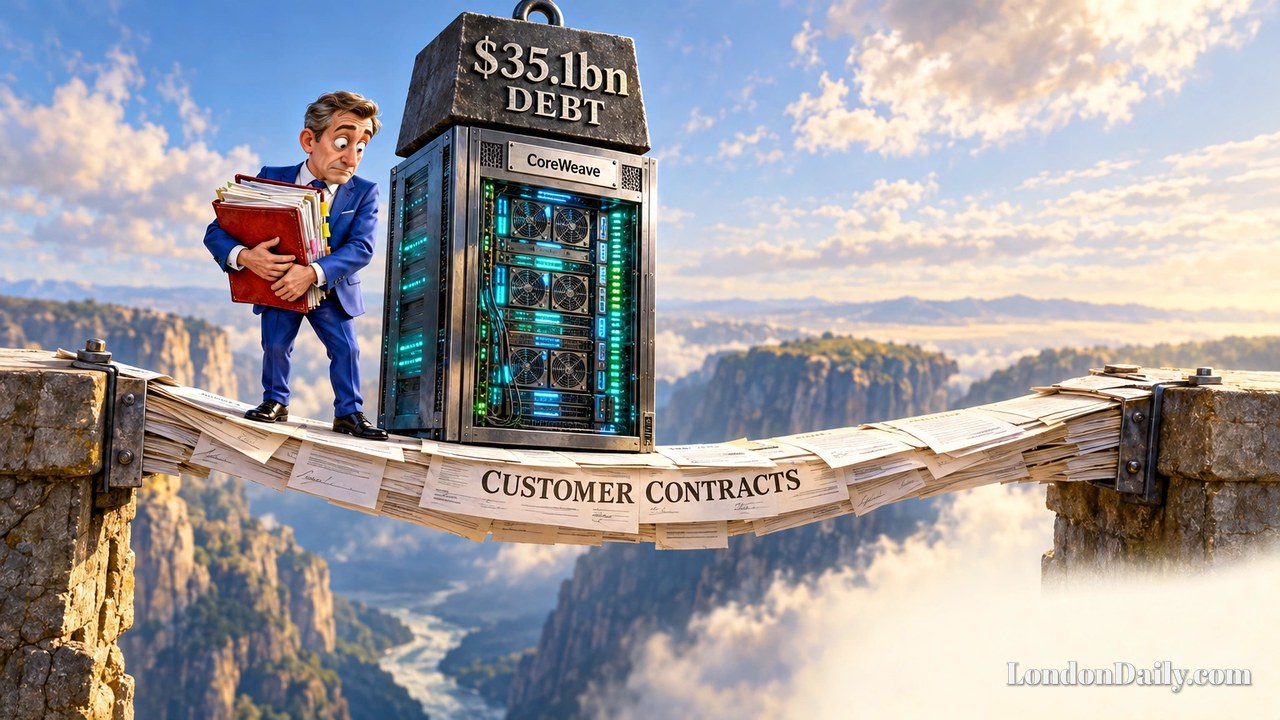
These businesses lease warehouses of expensive computers to customers including Anthropic, OpenAI and Meta. Their financing links today’s hardware bills to customers’ future spending: long-term contracts and purchased chips serve as collateral for borrowing.
Cory Johnson, an analyst at IPO research firm The Quiet Period, says lenders sometimes place more weight on customers’ creditworthiness than on the operator’s. That helps explain CoreWeave’s $35.1bn (£26.3bn) debt, he says. Hardware must be paid for upfront.
The vulnerability is that customers can change course. When Microsoft and Google forecast less AI spending than Wall Street expected this past week, several neocloud shares tumbled. Forrester analyst Charlie Dai says the model carries ‘greater financial risk’ when conditions change. Higher interest rates would add pressure.
Gartner predicts 80% of neocloud firms will ‘cease independent operations’ by 2030; Forrester expects at least three imminent acquisitions as finances weaken. Those forecasts concern independence, not necessarily the disappearance of their computing capacity.
CoreWeave chief executive Mike Intrator calls the market’s behaviour ‘irrationally’ driven and remains confident in its business model. Analysts at Yorkville Ives say computing demand still exceeds supply and neoclouds fill a gap larger operators cannot meet. On Thursday, US Treasury Secretary Scott Bessent described them as ‘a small component of the overall ecosystem’.
Yet heavy spending does not remove financing risk. S&P Global’s Melissa Otto describes an ‘arms race’. Venture capitalist Bradley Tusk warns neoclouds would suffer ‘collateral damage’ if an AI bubble burst. Elon Musk has predicted extensive consolidation among more than 200 operators, with smaller firms most vulnerable. These are warnings, not established outcomes.
Several operators, including CoreWeave, IREN, Core Scientific and Applied Digital, began in cryptocurrency mining, leaving infrastructure suited to the AI expansion following ChatGPT’s introduction in 2022. Nebius instead emerged from Yandex NV, splitting off and changing its name in 2024.
Practical constraints are already evident. Microsoft cancelled a deal with British operator Nscale amid power supply problems that could persist until 2030. Australia’s Firmus shelved plans for a public share offering, while Anthropic and OpenAI are expected to pursue listings in the coming months.
Public opposition to data centres and unresolved questions about AI’s productivity gains add uncertainty. Strong demand for computing power does not, by itself, establish that every supplier can finance its delivery.
Join the conversation