

Why the new global tax regime is unlikely to be clear, simple or good
The headline writers make it all sound so clear, simple and good: “World’s leading economies agree on global minimum corporate tax rate” said the Financial Times.
In truth, the tax plan is more likely to be messy, strangled by caveats and carve-outs, and a veritable feast for tax avoidance experts. At worst, it will crash and burn. At best, it seems likely to have little impact either on the taxes that companies pay or the revenues that cash-strapped governments hope to pick up.
This practical reality has not suppressed the breathless excitement after Group of 7 leaders provided a critical push to the long-wrangled initiative at their summit in Cornwall, Britain. The Financial Times said the proposed tax reforms should be “genuinely considered historic” and that they would “change a century’s worth of tax rules to ensure the largest multinationals pay more tax where they operate”.
However, the newspaper’s European economics commentator Martin Sandbu argued that the outcome “is mixed at best” and that “governments have missed an opportunity to simplify the rules, leaving fertile ground for new and clever techniques to circumvent their intention”.
The same newspaper’s economic team was even more underwhelmed: “If some of the most powerful multinationals have had a bomb put under them, you wouldn’t know it from their reactions – or those of investors.”
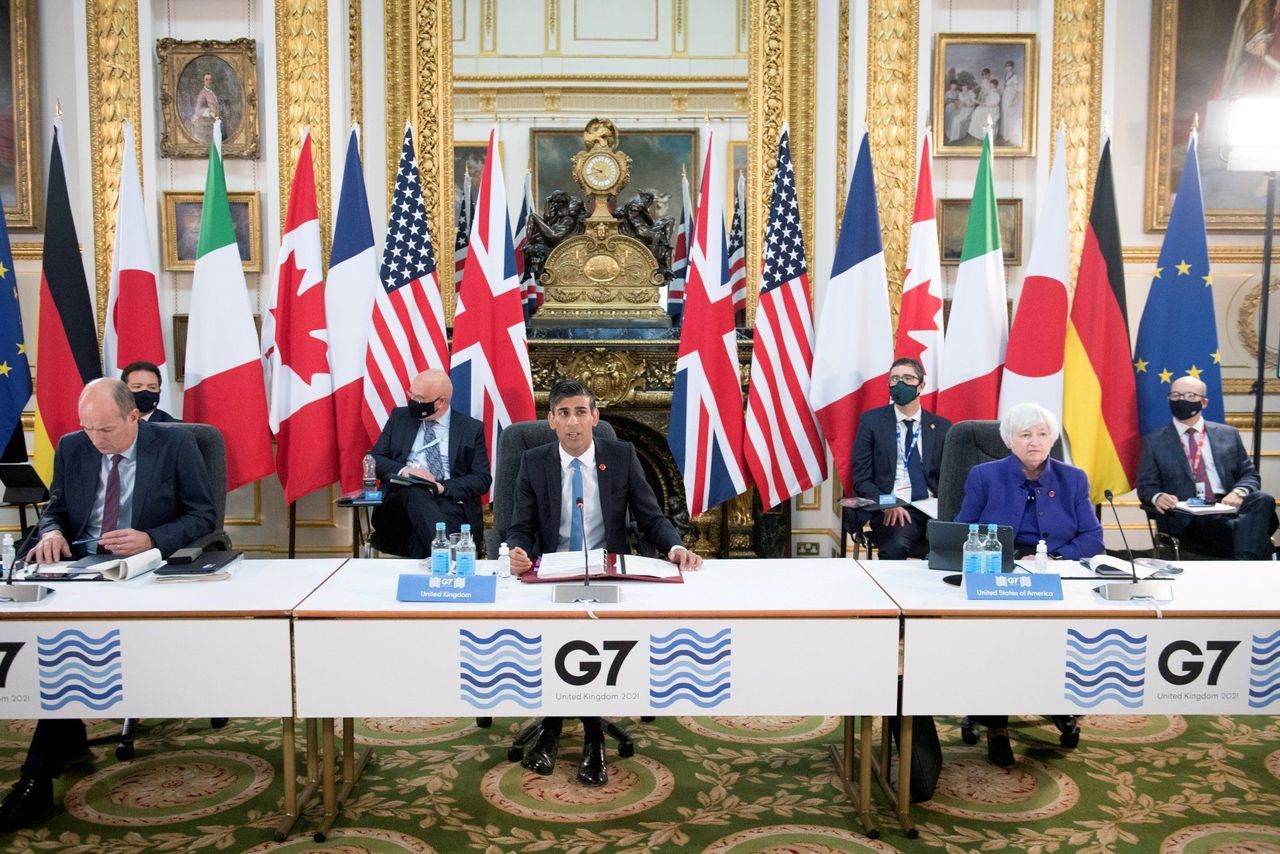 Britain’s Chancellor of the Exchequer Rishi Sunak speaks at a meeting of
G7 finance ministers at Lancaster House in London on June 4, ahead of
the Cornwall summit, where leaders agreed on a minimum corporate tax
rate proposal.
Their report said “the plan could upend some of the corporate world’s most widely-used avoidance strategies, while also throwing up a complex new set of rules for tax planners to get their teeth into”.
Scratch the surface of the proposed new tax rules, which had their origins in European frustration over the small tax payments made by the world’s most profitable technology groups, and you crash into complexity.
The proposed deal comprises two pillars. Most analysts like to tackle the second pillar first: a plan to set a minimum corporate tax rate worldwide at 15 per cent. That sounds straightforward, but it is not. For starters, there is serious dispute over whether the minimum tax rate should be set higher, perhaps up to 25 per cent.
The minimum rate would apply only to the world’s 100 largest multinationals, with turnover exceeding US$20 billion. There are already carve-outs for financial services and natural resources, and more battles over other carve-outs can be expected.
Taking the Fortune Global 500 list as an indicator of the companies likely to be targeted, you find that over 20 mainland Chinese companies sit in the top 100. But most of these are heavily focused on China’s domestic economy. International business accounts for little of their revenue. Unsurprisingly, most are unconcerned by the new tax plans, and the Chinese government has been relaxed about signing up.
Multinationals will only be bound by the new rules if they have a pre-tax profit margin of over 10 per cent, which is likely to encourage companies to raise reinvestment to suppress profit margins.
Intriguingly, the G7 has decided that the highly-profitable Amazon Web Services will be subject to the new rules even though its parent reports profits below 10 per cent. But what kind of cat-and-mouse games are going to be played by other giant multinationals over where profits and losses sit between the parent and the subsidiaries? Tax advisers must already be rubbing their hands.
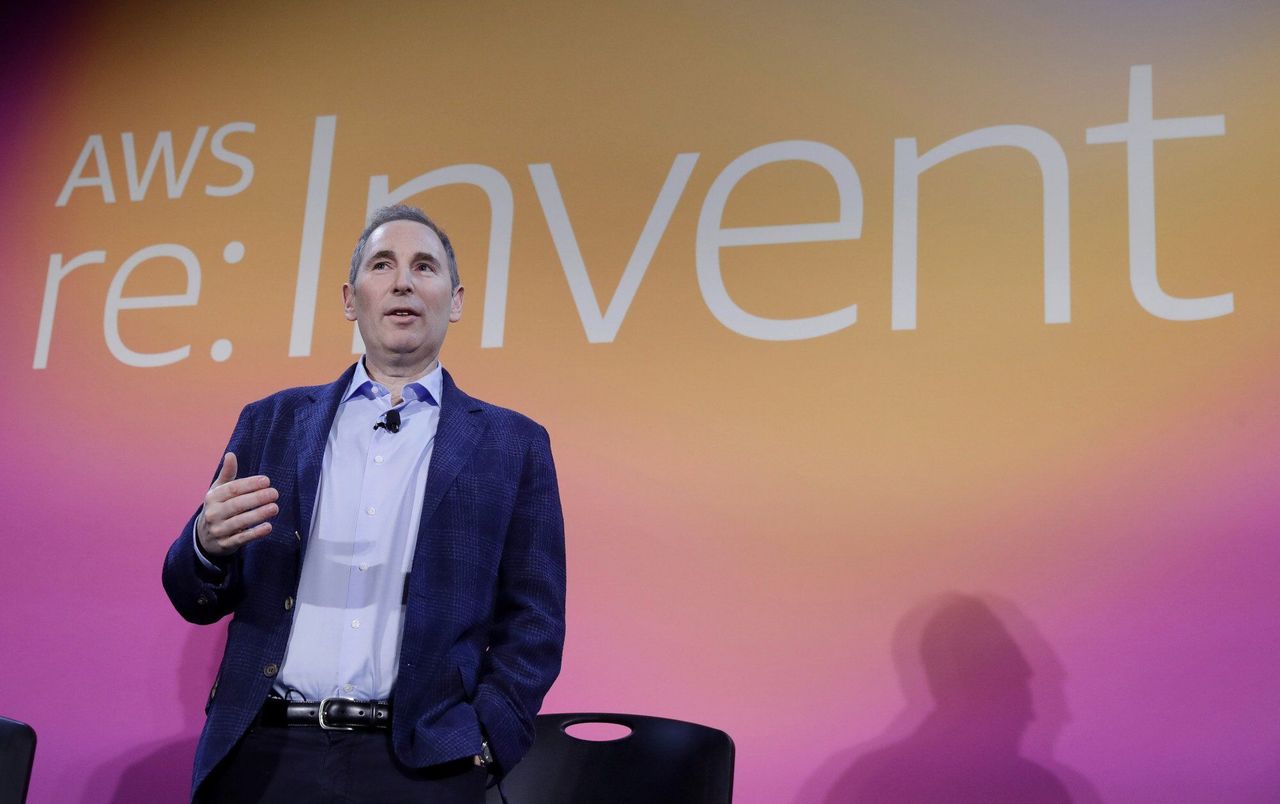 Andy Jassy, who took over as Amazon CEO in July, at an event in Las
Vegas on December 5, 2019, when he was heading Amazon Web Services. AWS
is Amazon’s cloud computing business.
As for the first pillar, which is focused on getting multinationals to pay taxes where they generate their revenue, rather than in the low-tax domiciles they so often select, the rules quickly become similarly obscure. The digital services tax introduced over the past year by governments such France and Britain to claw more taxes from the large US tech companies is promptly submerged.
Indeed, for the United States, dropping the digital services tax is likely to be a formal precondition of support for the new tax rules. At the end of the day, only 20-30 per cent of so-called residual profit above the 10 per cent threshold would be subject to tax in the countries where it is generated.
Even after endorsement of the plan at the G20 over the past weekend, there remains a long and difficult path ahead – not least, passage through a truculent US Congress. A meeting of 130 countries is to be called later in the year, and implementation will be 2023 at earliest.
If the new rules pass successfully, the main reason for this may be that for most economies, the changes make barely any difference. Look at where the US federal government gets most of its revenue, and corporate taxes account for a paltry 7 per cent. Individual taxes account for 50 per cent, and social insurance and payroll taxes 36 per cent. That perhaps explains why the Biden administration is pressing for corporate taxes to be raised to 28 per cent.
Look at China and Hong Kong, and the picture is a little different: corporate taxes already accounted for 21.8 per cent of Chinese tax revenues in 2019, individual taxes 6 per cent and excise and value-added taxes 52.9 per cent. For Hong Kong, corporate taxes accounted for 24 per cent of revenues in 2020-21, land premiums 16 per cent, stamp duty 15.7 per cent, and individual taxes 13 per cent.
In short, the new rules would probably make little difference to total revenues, even with rising pressure on governments to raise more revenues as pandemic borrowings have to be paid down.
Perhaps it is naive or foolish to expect anything different. Governments worldwide remain ferociously independent-minded over how they can raise taxes, how much they raise, and how they spend. For them to allow new multilateral rules to fetter this jealously guarded power would be political suicide.
So it should be no surprise, despite the melodramatic headlines, that the new rules are likely to change little. Tax rules will remain monstrously complex. Tax “management” will remain endemic. Some things in life cannot change.