LONDON DAILY ARCHIVE
Independent Review into UK Loan Charge Initiated
Government launches review to address concerns around Loan Charge and associated tax liabilities
25 January 2025 · 08:34 UTC
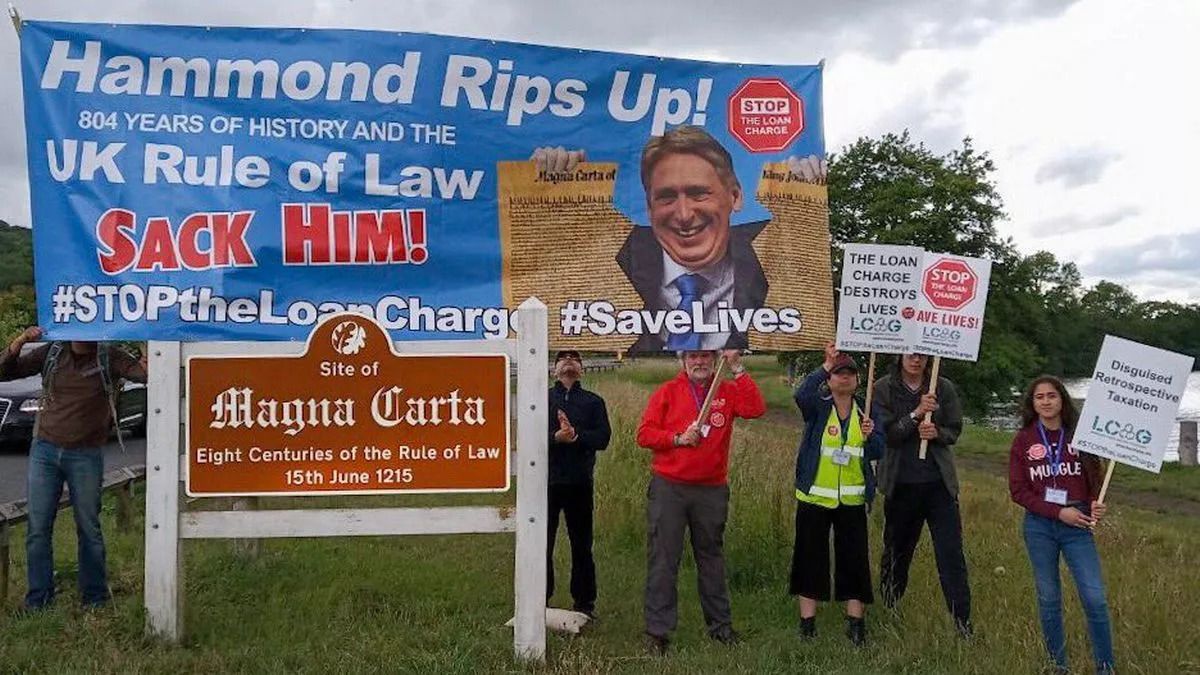
Announced in 2016, the Loan Charge was implemented to address issues relating to tax avoidance schemes that reclassified remuneration as non-taxable loans to circumvent income tax and national insurance contributions.
These tax avoidance schemes have been operational since at least the mid-1990s and have undergone judicial scrutiny.
In 2017, the UK's Supreme Court ruled in favor of HM Revenue and Customs (HMRC), affirming that schemes channeling earnings into loans do not effectively avoid taxation.
The government, consistent with the court's stance, maintains that those who underpaid tax should reconcile their accounts with HMRC.
Despite this, ongoing concerns about the Loan Charge have necessitated the new independent review, which aims to resolve these issues conclusively.
James Murray, the Exchequer Secretary to the Treasury, stated that the review honors the commitment to conclude the matter for those impacted, while ensuring equitable treatment for all taxpayers.
Ray McCann, former president of the Chartered Institute of Taxation, has been tasked by Mr. Murray to lead the review.
McCann reiterated the goal of the review, emphasizing the importance of reaching a fair resolution for involved parties that aligns with the tax compliance of the majority.
The initiative for the review was announced in the Autumn Budget of 2024, with the conclusive report expected by summer 2025.
However, the announcement has encountered criticism.
Conservative MP Greg Smith, co-chair of the Loan Charge and Taxpayer Fairness all-party parliamentary group (APPG), criticized the review’s framework, arguing it lacks independence, and expressed concerns that it does not adequately address the fairness or justification of the Loan Charge legislation.
The APPG has advocated for more comprehensive inquiries into the Loan Charge, emphasizing the need for a genuinely independent investigation, distinct from HMRC or Treasury oversight.