LONDON DAILY ARCHIVE
Increasing Trend of 35-Year Mortgages Among Young Homebuyers
Young homebuyers are increasingly opting for 35 to 40-year mortgages to manage the financial burden of home ownership. Nicola Webb, a nurse from Gloucestershire, bought her first property with a 35-year mortgage lasting until she is 68. Similarly, Shane Lees in West Sussex chose a 35-year mortgage term to buy a three-bedroom house, hoping to shorten it later. Though longer terms ease current repayments, they lead to higher overall interest and future financial challenges.
19 May 2024 · 09:37 UTC
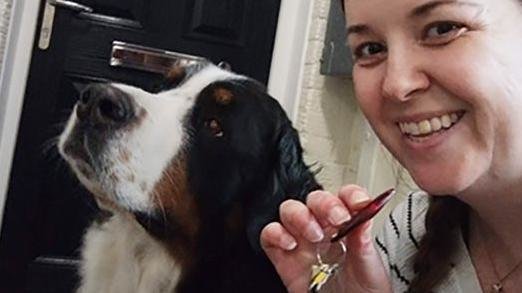
Nicola Webb, a 34-year-old nurse from Gloucestershire, bought her first property with a 35-year mortgage that will last until she is 68.
Despite saving a large deposit for her £147,000 two-bedroom flat, her five-year fixed rate mortgage costs her £598 a month, which is about a third of her monthly wages.
Nicola hopes to reduce her mortgage term once her student loan is paid off.
Shane Lees and his partner in West Sussex also opted for a 35-year mortgage term to buy a three-bedroom house valued at around £370,000.
They eventually plan to shorten the term after a two-year fixed deal.
Mortgage broker Martin Tapper and financial advisor Sarah Coles emphasize the importance of having a plan to manage these long-term commitments.
Tapper suggests a longer mortgage term can help escape high rent costs, while Coles advises having a plan B for life's uncertainties.
Data from the Bank of England shows a rising number of younger homeowners taking out mortgages that extend into retirement.
The trend has seen a significant increase for those under 30 and 40.
While longer terms can make repayments more manageable now, they will result in higher overall interest payments and potential financial challenges in retirement.